
Table of Contents
Combined live, under-construction and planned capacity reached 1.95GW, making Paris EMEA’s third-largest market on that basis, according to a recent report by Cushman & Wakefield
In sum – what to know
Pipeline tops 1GW – Paris has 665MW of operational capacity, 278MW under construction and more than 1GW planned, taking combined capacity to 1.95GW.
Demand remains strong – 65MW of colocation capacity was added year on year, with about 46MW absorbed, equivalent to 71% of new supply.
Grid limits growth – Local grid capacity and connection timing remain constraints as larger sites move toward outer Île-de-France.
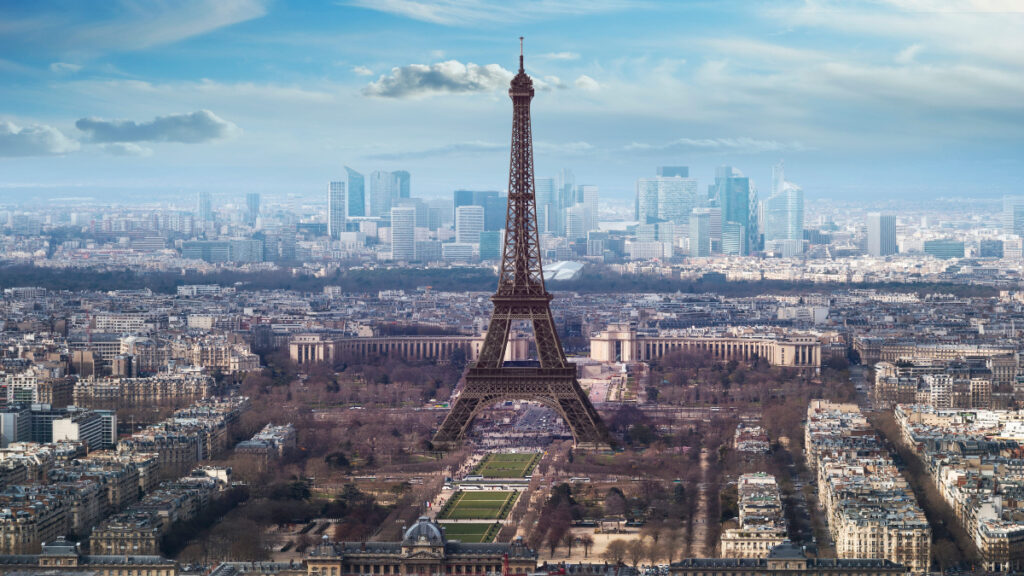
Paris is entering a new phase of data center development, with larger wholesale, hyperscale, and AI-focused campuses becoming increasingly prominent in the market’s pipeline.
The Paris data center market had 665MW of operational capacity in the second quarter of 2026, up 65MW year on year, according to Cushman & Wakefield’s EMEA Data Centre Update H1 2026. Capacity under construction rose 23% to 278MW, while planned capacity exceeded 1GW.
Combined live, under-construction and planned capacity reached 1.95GW, making Paris EMEA’s third-largest market on that basis, despite ranking fifth by operational capacity. Growth is also spreading beyond Aubervilliers, Nanterre and Vélizy toward larger sites across outer Île-de-France, where more land and higher-capacity power connections can be secured, according to the report.
Colocation accounts for 97% of operational capacity, with wholesale representing 72%. Digital Realty is the largest operator, with 142MW across 13 facilities, followed by DATA4 with 120MW and Equinix with 107MW. CloudHQ operates 74MW, while Global Switch, OpCore and KDDI Telehouse each have between 29MW and 37MW.
The three largest operators account for 55% of live capacity, although the pipeline includes a wider range of operators and larger campus developments.
Self-build hyperscale capacity remains limited, with cloud providers having historically relied on Paris’s wholesale operators. The early-stage pipeline now includes a potential 200MW AWS self-build project in Tigery, signalling growing interest in directly owned capacity.
French platforms such as DATA4, OpCore and OVHcloud are also becoming more strategically important as France seeks greater control over the infrastructure used to store data and train AI models, according to Cushman & Wakefield.
The development is closely linked to France’s ambition to strengthen French and European AI sovereignty. At the February 2025 AI Action Summit, France announced €109 billion of prospective private investment, much of it linked to computing infrastructure.
Further announcements include an €8.5 billion open AI campus involving MGX, Bpifrance, Mistral AI and Nvidia, alongside four Prologis projects around Paris totalling 584MW. The aim is not only to attract international capital but also to provide domestic AI companies with access to computing capacity currently concentrated among U.S. hyperscalers.
Demand for existing capacity remains significant. A total of 65MW of colocation capacity was added year on year, of which about 46MW was absorbed, equivalent to 71% of new supply. Available capacity consequently increased from 18MW to 37MW.
As of the second quarter of 2026, 54% of capacity under construction was preleased, while planned capacity remained almost entirely uncommitted. Paris has historically offered a broad choice of wholesale operators, with hyperscalers expanding through multiple providers rather than anchoring large campuses at an early stage.
Projects are therefore likely to proceed in phases, depending on customer commitments, grid certainty, and permitting.
France’s nuclear-heavy generation mix gives Paris an advantage in low-carbon electricity, but local grid capacity and connection timing remain constraints.
Since May 2026, strategically important data centers can qualify as “Projects of Major National Interest,” enabling simplified planning procedures and greater state involvement. However, projects must still comply with regional land-use policy and environmental requirements around energy, water and waste-heat reuse.
Local opposition is also growing where data centers compete with other land uses, meaning delivery will depend on reconciling national ambition with local planning and infrastructure constraints.