
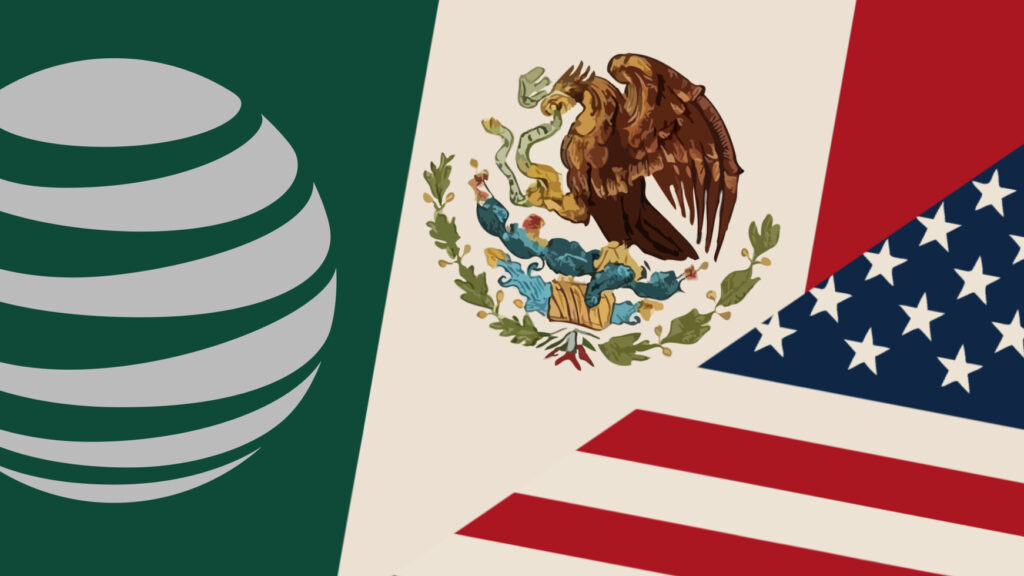
AT&T is leaving Mexico with $2bn in cash and a simpler story to tell investors. The US firm has agreed to sell AT&T Mexico to Grupo Televisa and Fintech Holdings, ending a decade-long bid to build a scaled wireless business south of the border. The official explanation is familiar enough for all sorts of toughened telcos in all kinds of mature markets: jettison the extra-curricular stuff, especially abroad, to concentrate capital and sharpen focus at home. See also: Telefónica has exited Argentina, Chile, Colombia, Ecuador, Mexico (also), Peru, Uruguay; Vodafone has sold its Spanish unit and its stake in VodafoneZiggo; Etisalat has cashed out of Vodafone, and is reviewing other investments; BT has sold its Italian and Irish operations and bundled international business into a venture with Verizon. See also Nokia. There are others.
With AT&T – less Mexi-can, more Mexi-can’t – there is some smart logic. But there is also a counter-intuitive financial catch – as observed by BNP Paribas, which puts AT&T Mexico’s expected 2027 EBITDA at about $900m, implying a sale multiple of “just” 2.2 times. It estimates the business generates around $500m in annual cash, which AT&T won’t receive after the sale (Q127). Lower debt and interest costs could soften the blow, but the disposal is a trade-off between recurring cash flow and a focused business. The effect might be broadly neutral if investors reward the remaining company with a higher valuation multiple – which BNP Paribas reckons they will. AT&T might sell a profitable business, on the cheap, without taking much of a hit. It is betting investors will reward simplicity – which is the story every telco wants to tell. The problem is it will have nowhere to hide.
BNP Paribas writes: “The sale is not much of a surprise – it’s a low multiple… [but] we think there’s enough upside on the core AT&T business to maintain guidance… Offloading the business reduces organizational complexity for AT&T and allows it to focus singularly on its domestic comms business. At the same time, because AT&T will only have domestic operations after the sale, it does simplify the AT&T equity story.” As said, the deal fits a wider retreat from the idea that telcos must build and maintain substantial businesses across multiple markets to achieve growth. AT&T entered Mexico in 2015 (via Iusacell and Nextel Mexico), and built a business with almost 25m subscribers. Now it is handing that operation to owners with a more direct local rationale: Grupo Televisa already has a substantial fixed-line broadband presence, while Fintech Holdings brings capital and Mexican market experience.
Operators have to decide where they can earn adequate returns from expensive network assets, where they can establish a defensible position, and where capital might work harder elsewhere. Geographic expansion is no longer a virtue in itself. For AT&T, it means doubling down on the US. Its argument is that dense fiber assets and wireless connectivity will be central to the AI economy, linking data centers, enterprises, consumers. But competitive boundaries in its home market have blurred, also. It has a fight on its hands, perhaps; SpaceX is pushing Starlink as a more direct challenge to terrestrial operators, with up to 14MHz of paired 800MHz spectrum in the bag to add a (very thin) terrestrial coverage layer, and the green light to multiply its LEO constellation. As we have written, satellites are not about to replace AT&T et al, or compete for dense urban business, or displace the fiber that underpins them all.
But there is an incremental battle at the fringes, starting in the coverage black-spots and not-spots throughout the US, and Starlink’s latest spectrum acquisition has unsettled investors. The FT puts the combined market-value losses for AT&T, Verizon, and T-Mobile at roughly $60bn following SpaceX’s deal with Grain Management. So AT&T faces a strategic paradox. It is concentrating its resources on the US because it sees the market as the best place to invest, while a new challenger is changing the market economics almost behind its back. Starlink is not why AT&T is selling Mexico; the deal has been presented as part of a strategy set out at an analyst day in 2024. But the move makes the domestic business more central to AT&T’s future – just as the home fires burn bright with promise, and get drafty on the winds of change.

James Blackman
Executive Editor
RCR Wireless News
RCR Top Stories
Nokia keeps drones: Nokia has excluded its drones unit from the sale of its campus private 5G business to Aurelius. The drones business is under review, it said. Its MPW platform goes with ECE , but will be resold by Nokia also.
Which AI-RAN? The AI-RAN investment case changes with where capacity is constrained. Software on installed RAN has the clearest near-term economics, while accelerated platforms depend on paid utilization, falling inference prices, and more.
Quantum networks: Singtel sees quantum security as a migration challenge rather than a future technology issue, combining QKD, post-quantum cryptography, and ecosystem coordination to prepare telecom infrastructure.
AI-RAN blueprints: The AI-RAN Alliance is expanding its focus on AI RAN services while tackling workload placement, infrastructure sharing, and the commercial case for turning mobile networks into distributed AI platforms.
US fiber race splits: AT&T is folding Gigapower and Lumen’s fiber assets into a joint venture half owned by GIP and CPP Investments. The deal shows the different strategic paths AT&T, T-Mobile, and Verizon are taking in the fiber race.
AI-Powered Telecom Infrastructure
Supermicro, in collaboration with NVIDIA, delivers AI-powered infrastructure tailored for telcos, enhancing operational efficiency, network management, and customer experiences. Explore now
Beyond the Headlines
Campus retreat: Nokia’s sale of its ECE business gives Aurelius a 1,000-person industrial networking operation to grow, while simplifying Nokia’s focus on mobile and network infrastructure. The deal also exposes the limits of telco-led private 5G.
AI goes mobile: Deutsche Telekom chief Rodrigo Diehl has said AI, physical AI, 6G, and network orchestration will reshape telecom networks, increasing demand for quality, intelligence, sensing and autonomous operations.
VDF, by numbers: Vodafone’s investor day revealed the scale and shape of its enterprise business, from £1.85bn in annual service revenue to growth bets on network slicing, FWA, SD-WAN, cloud, and security.
MNO ‘earthquake’: SpaceX’s deal for 800 MHz spectrum strengthens Starlink Mobile’s push into terrestrial wireless. But coverage is not capacity, and building a competitive nationwide network could cost tens of billions of dollars.
Telco AI $$$ TBD: Telcos are holding back on AI-RAN’s headline promises of edge AI revenue and shared compute, focusing instead on measurable gains in spectral efficiency and automation while demanding proof of customer demand.
What We're Reading
Sovereignty hoax: Sovereignty claims lack evidence, says an Omdia study of 35 providers in 20 countries, citing weak service guarantees and accountability for resilience. It warns data sovereignty must extend to connectivity, not just hosting.
NTN IoT chipsets: Altair Semiconductor is integrating satellite IoT from Iridium into its cellular chipsets, enabling devices to switch between terrestrial and satellite coverage without a separate modem.
LTE robo-deliveries: Deliveroo will launch LTE delivery robots in the UK, starting in London, moving to Milton Keynes, Leeds, Stockton-on-Tees, Nottingham. It is using Coco Robotics, which announced a deal in March for LTE modems
‘Yes’ to tower sale: Liberty has EC clearance to sell VodafoneZiggo’s passive tower assets to DigitalBridge, TD Greystone Infrastructure, and L&G for €669m. The deal is expected to close by year-end.
Roaming deal: BICS will manage Proximus SA’s roaming negotiations. The firm, part of Proximus Global, will consolidate commercial discussions with global operators to simplify partner relationships and roaming management
Latest RCRtv Interviews
Events
Industry Resources
RCRTech Trend
WiFi driving Telco growth
RCRTech Trend
Rise of Non-Terrestrial Networks (NTN)