
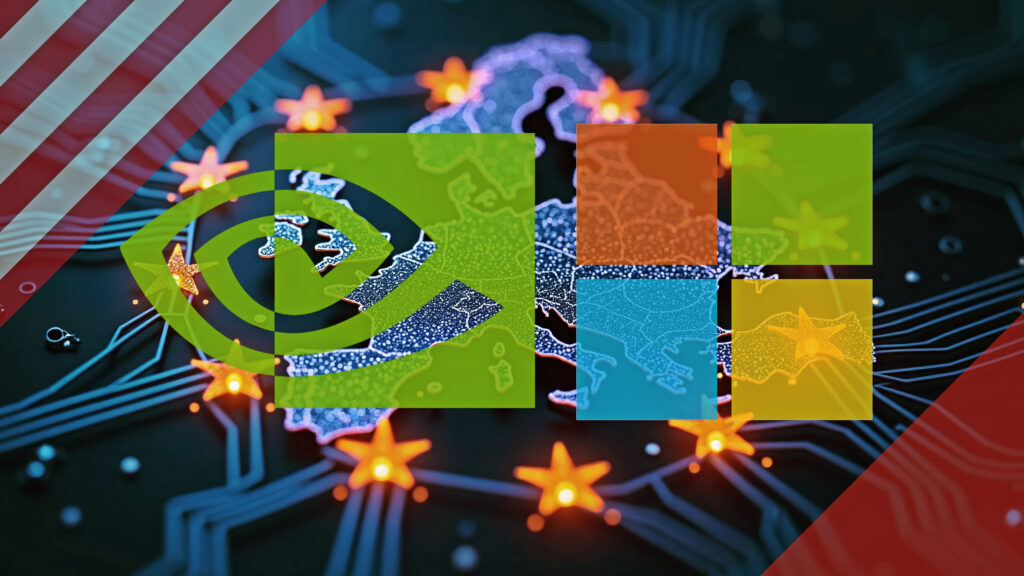
If tech sovereignty wasn’t already smack-bang at the top of the political agenda, it must be now – bound up with geopolitics and foreign policy, domestic security and political stability, and questions about the future of work and society. In a matter of days, critical failures at two of the pillar firms in the supposedly stable and trusted ‘western’ AI tech stack – both American – have exposed uncomfortable truths about the ball-of-snakes corporate monopoly at the heart of the all-consuming AI industry. Nvidia is being scrutinised following allegations linking its leader – Jensen Huang, the pied-piper for the whole AI song-and-dance – to an alleged Chinese spy. Microsoft has suffered a major outage – Thursday into Friday, unresolved at press – that has knocked out Microsoft 365 services in dozens of countries. There is no suggestion that Nvidia was robbed or Microsoft was hacked.
And neither episode, on its own, makes a case to turn away from US tech. (Nvidia and Microsoft are more than a match for their European equivalents, if they exist, on security and resilience.) But both illustrate the risk of placing so much faith, and so much critical infrastructure, in the hands of such a small number of service providers. There are three strands to the sovereignty debate, vexing Europe most notably: where the AI runs, who controls it, and what it runs on. Europe, in an existential wrangle about its position in the world, and a late charge for some kind of impact in the AI race, is making progress on the first two. European telcos have placed themselves into the middle, as good corporate citizens and trusted guardians of sovereign data. They are variously building AI ‘factories’ as alternatives to the likes of Microsoft, while also working with them on separate cloud initiatives.
But the third strand is harder, verging on impossible, and eludes the telco set completely. Deutsche Telekom is the best example: it is putting another €250m into its AI factory in Munich, taking capacity to 20MW with Nvidia’s latest Blackwell systems – after the first phase was booked-out in seven months. Otherwise, its so-called Deutschland Stack is largely true to its name: made in Germany. Paderborn-headquartered Polarise is responsible for the design, build, and operation of the data-centre infrastructure; SAP provides the software platform; Siemens, among others, is handling industrial AI applications. The site is host to the European SOOFI project, geared to develop independent AI foundation models for Industry 4.0. There are other telco examples, organised differently: Orange, Fastweb, Swisscom, Telenor, and Telefónica are all building sovereign capacity. The commercial opportunity is clear.
The third-strand technological independence is much less so. They might have control of data residency, and maybe even the ‘kill switch’, but most are using the same foreign chips from Nvidia – whose leader is embroiled in a political scandal with a suspected Chinese spy. Nokia wants to put the same into European RAN systems – which are, meanwhile and separately, under pressure from EU security policy about ‘high-risk’ Chinese suppliers. Even SK Telecom’s work with domestic chipmaker Rebellions to develop sovereign AI inference infrastructure can’t avoid Nvidia: its proposed system will combine Rebellions’ own NPUs with Nvidia’s GPUs, and also use the latter’s NVLink Fusion interconnect and MGX rack architecture. The proposal, still at MoU stage, localises a part of the compute stack, but Nvidia is still central to the design. It shows how tightly wound the global tech industry is, and how conditional sovereignty can be.
There is another Nvidia dependency beyond the hardware, of course: money. As Vish explores in his excellent analysis of its post-Huang position as underwriter of the AI boom, the company’s influence extends heavily into the industry’s financing arrangements. Who funds the GPUs, who guarantees the demand, who carries the risk – if these mystical AI returns don’t materialise? For European operators, sovereignty is therefore not simply a question of where the machines sit, or even who owns them. It is also – and increasingly, given security questions around cornerstone companies, and (new) hyperscaler blackouts – about who supplies the tech, who controls the supplies, and who writes the cheques. Europe is making progress to build its own AI infrastructure. Whether it can exert much real control over the industrial and financial machinery behind it seems like a dicier question.
James Blackman
Executive Editor
RCR Wireless News
RCR Top Stories
Post-Huang AI: Nvidia’s financing guarantees are under scrutiny following its leadership upheaval, raising questions about whether smaller AI cloud providers can secure funding for new GPUs. A slowdown could shift compute capacity.
DT scales AI: Deutsche Telekom is expanding its Munich AI factory with Nvidia Blackwell Ultra systems, responding to demand while advancing its broader ambition to generate AI-related revenue from enterprise services and infrastructure.
Sovereign SKT AI: Nvidia, Rebellions and SK Telecom have signed an MOU for Korean sovereign AI inference. The R200 details remain undisclosed, and the Huang scandal overshadowed the signing.
Agentic skills: The value of agentic AI in enterprise operations depends on whether agents can bring together the right expertise, tools, and evidence for the problem at hand, writes Cisco ThousandEyes.
UE Logo 2.0: China Mobile is leading the UE Logo 2.0 deployment, with Huawei participating in the technology ecosystem alongside device and chipset partners.
AI-Powered Telecom Infrastructure
Supermicro, in collaboration with NVIDIA, delivers AI-powered infrastructure tailored for telcos, enhancing operational efficiency, network management, and customer experiences. Explore now
Beyond the Headlines
VDF in business: Vodafone has upgraded guidance after delivering 5.8% organic service revenue growth, with its Africa unit and enterprise digital-services mix driving momentum, while Germany remains a drag and further job cuts loom.
TIM integration: Telecom Italia is advancing integration with Poste Italiane, renewing its proposal to Inwit and evaluating FWA and satellite to extend connectivity where fiber access is unavailable.
MDU landlords: Europe’s 6.8m largest MDUs are dominated by social and public landlords, not private investors. Research maps the landscape and explains what it means for fibre, managed Wi-Fi and smart-building providers.
Freeport 5G is live: Verizon has completed a five-site private 5G deployment across Thames Freeport – 8 months after the deal was announced. The project spans ports, logistics, and manufacturing, and features a big pipe of industrial apps.
SKT advances 5G: SK Telecom plans to commercialize 5G Standalone in December, while evaluating 5G-Advanced and advancing 6G research as its focus on higher-value subscribers supports mobile revenue recovery.
What We're Reading
New AT&T HQ: AT&T has broken ground on a new global HQ in Texas, a 54-acre, seven-building campus with the installation of its first fiber connection. The 2.2m square-foot site will include extensive 5G coverage.
Telia acquisition: Telia is to acquire Telavox’s Nordic enterprise base for SEK3.8bn, plus a potential SEK200m earn-out, adding 24,000 businesses and 325,000 users across four countries, alongside a UCaaS platform licensing deal.
Nokia uni fund: Nokia is donating €1.5m to Finland’s Aalto University and increasing annual R&D collaboration worth €1.3m, backing research into 6G, AI, semiconductors, and resilient networks, while strengthening its talent pipeline.
Subsea VodaThree: VodafoneThree is studying a subsea cable between Scotland and Norway, with the UK-Norway digital corridor potentially generating £8.2bn in economic value over 10 years and strengthening connectivity resilience.
GenAI economics: Gen AI prices have fallen, leaders are losing ground, and startups captured 63% of app revenue in 2025, says a new report from CCIA – which argues competition is working and pre-emptive regulation is unwarranted.
Latest RCRtv Interviews
Events
Industrial Wireless Forum, November 10th, Virtual
From private 5G, Wi-Fi and public cellular to edge AI, spectrum, next-generation IoT and sensing, the forum examines the infrastructure choices and practical challenges shaping the future of industrial operations. Register now
AI Infrastructure Forum, December 8th, Virtual
Join RCRTech’s AI Infrastructure Forum to explore how telcos, hyperscalers and data centres can compete or partner as AI shifts to inference, and who captures the value when every token counts. Register now
PTC’27, 17-20 January, 2027, Honolulu, Hawaiʻi
PTC’27 is the premier event for digital infrastructure, telecoms and ICT. Executives, investors and researchers meet to share knowledge, build relationships and drive new business. Register now
Industry Resources
RCRTech Trend
WiFi Driving Telco Growth
RCRTech Trend
Rise of Non-Terrestrial Networks (NTN)