
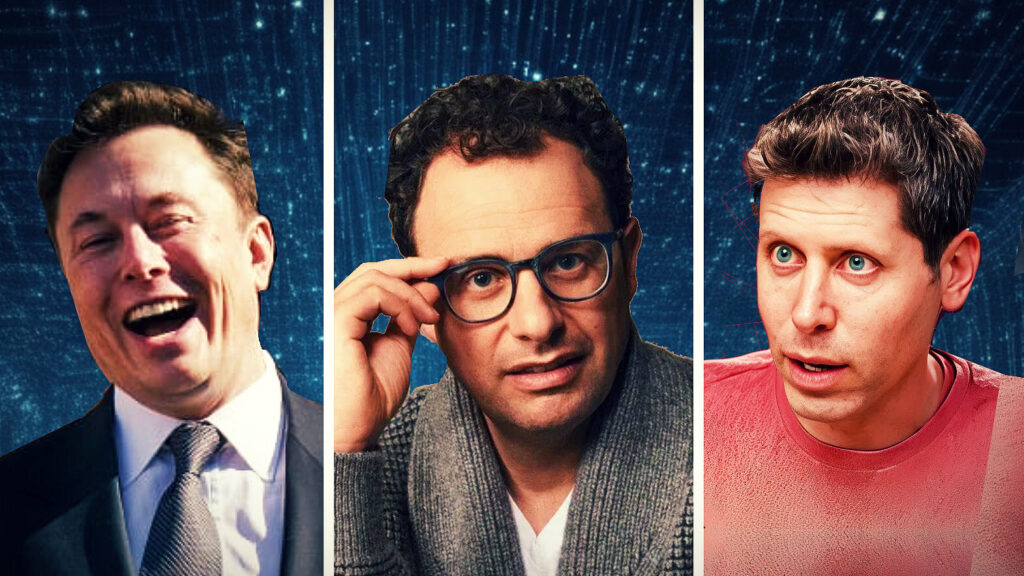
I’m not sure how helpful this AI ‘scaremongering’ really is – if your start-position, even vaguely, is to worry about democracy, society, humanity, and their disruption by rapacious trillionaire power-hoarding. I mean, if we park the telco narrative momentarily, and consider what everyone – the mainstream press, the social media commentariat – has said about an AI armageddon since yesterday, since Anthropic boss Dario Amodei called for a slow-down in frontier development, and his peers agreed, then it is also worth considering whether to take their word for it.
Not so much about whether the horse is about to bolt because we surely know that already. The capability/risk curve is almost too steep, getting steeper, for putative AI safety mechanisms to be developed in response, let alone agreed upon and enforced – as Amodei wrote in an open letter, and as Sam Altman and Elon Musk echoed. AGI definitions vary wildly, and timelines for it have moved in and out of view; but the concept of recursive self-improving models operating via distributed agents with invisible hooks in critical infrastructure no longer sounds like sci-fi.
There is a genuine safety argument, and there has been for ages. So on the face of it, this is not a financial stunt; Bernie Sanders and Naomi Klein would argue for the same, at least. But if we accept this new business ‘elite’ are looking after their business interests (even if we can’t agree that they are self-serving, power-crazed, or corrupted) – that they are business-men (to a man) – then we should also ask what the horse is being bred for, and for whom (etc). And we should consider the timing, which seems curious – surely?
The AI labs need the economics to work, and fast. Right now, they don’t. They have built businesses around a remarkable proposition: spend extraordinary sums on compute power today to deliver ever-more capable AI tomorrow – to create spiralling business value down the line. This conceit requires eye-watering amounts of capital, and total investor confidence. And the questions are getting harder. How much revenue for each dollar of compute? When does AI produce results for enterprises? How much enterprise revenue is incremental, rather than experimental – for keeping up with Jones & Co? When does the cap-ex turn into cash?
The market wants to know. Its reaction to the slow-down rhetoric wasn’t a response to an ethical debate, but to an existential one – in a purely economic sense. Big-tech AI cap-ex is projected at $795bn in 2026, and $1.08tn in 2027, according to Bank of America Global Research (quoted in the Reuters piece); semiconductor stocks have been heavily sponsored by that spending so far. It is a monster-sized machine to keep running. Is the bubble about to burst? Nvidia fell 3.4% on Monday; Softbank fell 10.7%; the whole semiconductor complex was hit pretty hard (although it is still 60% up for 2026).
Have the industry’s own safety fears sharpened the pin? No, because the market already knows the rumour – that big-ticket AI is not delivering. The drugs might work, but what’s the high? Gartner says 22% of firms have scaled AI across business units, or adopted an ‘AI-first’ approach – despite 85% planning to increase their spending. A survey by Futurm says 47% of enterprises are over-budget, and only 17% are ‘slowing down’. So a good amount of AI spending, lots of blind hope, and a fair amount of over-spending as well – but limited success, by any measure.
The Open Future Forum found a 28-point gap between CEOs expecting measurable AI payback within six months (70%) and CFOs expecting the same (42%). ‘Proving ROI’ is the biggest blocker to additional AI spending, it suggests. (Which is a perfectly familiar pattern, of course – if you’ve read the recent narrative in here about 6G, private 5G, IoT, all the rest.) What is clear is that the money is going out faster than it is coming back in. All of which – safety concerns, running costs (plus supply-chain shortages, energy constraints, regulatory intervention), jittery investors with lots of questions – makes their position look loaded.
Like the AI labs might benefit from slowing the race – to preserve their own leads. If the frontier stabilises, then so does the competition (to invest and leapfrog), and existing models become more valuable, and existing infrastructure investments have time to earn money back. The reality catches up, the bubble stays put – and crazy money-spinning IPOs might be back on the table. Criminally, China has been missed from this discussion, but there is surely an economic incentive to these companies to loosen the reins, slacken the race.
Which is funny, because SpaceX spoke last week at a Goldman Sachs tech event – an (AI) transcript is available here; a write-up of an AT&T discussion from the same show is here – and said the opposite: that the build-out won’t slow down, however it is leveraged by frontier firms (including its own) for training. Amid some two-way posturing with AT&T et al about old/new telco dynamics (dinosaurs versus aliens; search the previous links for both sides), SpaceX was almost-comically bullish.
Where the frontier labs are talking about a slow-down, Bret Johnsen, CFO at SpaceX, said SpaceX is planning 5-10GW of terrestrial compute in 2027; where the analysts say the enterprise returns aren’t there, SpaceX is targeting $100bn ARR, and thinks AI demand will continue “up and to the right”; where the market wants to know if any of this will actually generate any money, SpaceX says, effectively, ‘don’t worry; we’ll stick it in the sky’. So what exactly is slowing down here?
If it is model development, then SpaceX might still be right about demand for agents and inference workloads. If it is AI monetisation, then its 5-10GW bet looks like a gamble. If it is enterprise adoption, then the whole buildout is speculative – as it was from the start. If it is investor enthusiasm, as a consequence, then the cap-ex gets even more expensive. If it is all of the above, all at once, then the bubble bursts. But the AI boom also doesn’t have to be fake for the AI trade to be overextended – as we have written in these pages about all the telco hype categories.
You can have brilliant tech and awesome demand – and still spend too much, too quickly. Sorry, longer than intended.

James Blackman
Executive Editor
RCR Wireless News
RCR Top Stories
Rethinking 6G: Verizon says 6G will require a fundamental rethink of uplink capacity, device power, spectrum, and network architecture, with Los Angeles 2028 providing a critical real-world test.
Digital skills: Closing the digital skills gap could add $3.5tn to global GDP as AI reshapes digital participation and creates new literacy requirements. So says GSMA Intelligence, in collaboration with Huawei.
Saudi AI push: AWS and Mistral are expanding their work with HUMAIN, combining local cloud and AI infrastructure with sovereign models, compute capacity, and Arabic-language development as Saudi Arabia builds AI capabilities.
Compute demand: Nebius says AI compute demand continues to outstrip physical supply, prompting the company to expand data-center capacity through its own builds and partnerships with infrastructure owners.
TSMC buildout: TSMC is building 25 facilities at five times its normal run-rate, yet AI demand still outruns supply as equipment and capex climb. Advanced packaging, equipment, materials, and energy are critical bottlenecks.
AI-Powered Telecom Infrastructure
Supermicro, in collaboration with NVIDIA, delivers AI-powered infrastructure tailored for telcos, enhancing operational efficiency, network management, and customer experiences. Explore now
Beyond the Headlines
Clubs and duds: Verizon is expanding its 6G Innovation Forum as operators hunt for AI use cases and a credible case for next-gen cellular. But private 5G (and IoT and lots else) offers a warning: success rarely comes as a big industry windfall.
Telco roots: AT&T offers a grounded (sounding) vision for the AI era for telcos: build better fiber and wireless networks, pursue DCI selectively, and make existing infrastructure work harder rather than just chase the ‘supercycle’ bandwagon.
Campus strategy: Nokia’s new Cognitive Operations and Edge Node look strikingly familiar as the company exits private 5G – raising questions about product overlap, strategy and whether Nokia is quietly separating AI from network access.
Just not cricket: The telco opportunity in AI infra is fraught with weird economics, new competition, and a blurring of boundaries – even as networks become programmable, distributed, and optimized for the AI economy.
A big AI deal: Verizon is buying 80m miles of Corning fiber through 2032 as it builds a converged network for broadband, mobile, enterprise and AI data-center connectivity – betting on fiber as the physical foundation of the AI economy.
What We're Reading
Cambium admin: Cambium Networks has entered administration after running out of cash, cutting 54% of its workforce (260 jobs); administrators are seeking buyers for its last assets. A good write-up from RCR columnist Adlane Fellah on LI.
Pluggable optics: Telxius is deploying Nokia’s 800G coherent pluggables across across its terrestrial transport networks in the EE, US, and LatAm – following a record demo of Nokia’s ICE-X 800G optics over its BRUSA subsea cable.
Kansas upgrade: Nex-Tech Wireless has appointed Ericsson to upgrade around 85% of its rural Kansas RAN under a four-year deal, alongside deploying a cloud-native 5G standalone core and enabling network hosting for other operators.
Double swoop: Ondas is buying Israeli defense firm GATE Technologies and European manufacturing affiliate Bron Technologies for $205m, plus up to $185m in earn-outs, targeting $130m in combined adjusted EBITDA through 2028.
Mission-X agents: Mission-critical ops is “radically” different to enterprise IT ops for AI agents, writes Appledore in a free whitepaper – covering aspects of semantics, knowledge planes, ontology, trust in agentic systems. Worth a read.